


In today’s rapidly evolving economic and market environment, having clear, data-driven insights is essential. This collection brings together a focused set of charts and tables drawn from Wells Fargo Investment Institute’s broader Market Charts presentation deck, highlighting the key trends shaping the path forward for the economy and financial markets.
Key takeaways
- In our view, earnings growth will drive further gains in U.S. stocks through 2027, despite headwinds created by higher long-term interest rates tied to solid economic growth, sticky inflation, and increased U.S. Treasury debt to fund outsized deficits.
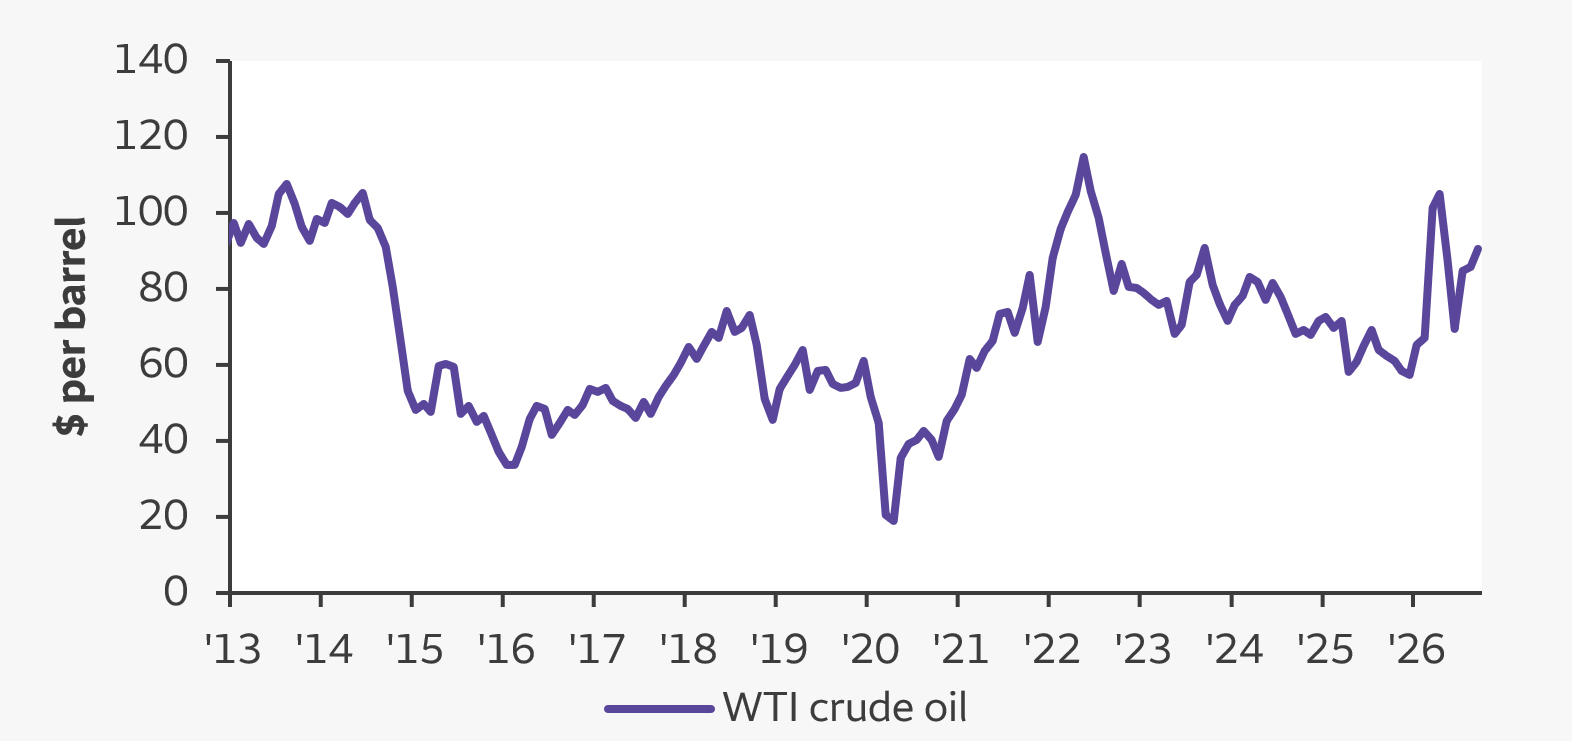
- We believe oil prices will gradually ease in 2027 as war-related “risk premiums” fade and major oil producers, including OPEC+1, ramp up production. We view supply-demand fundamentals as stronger for industrial metals.
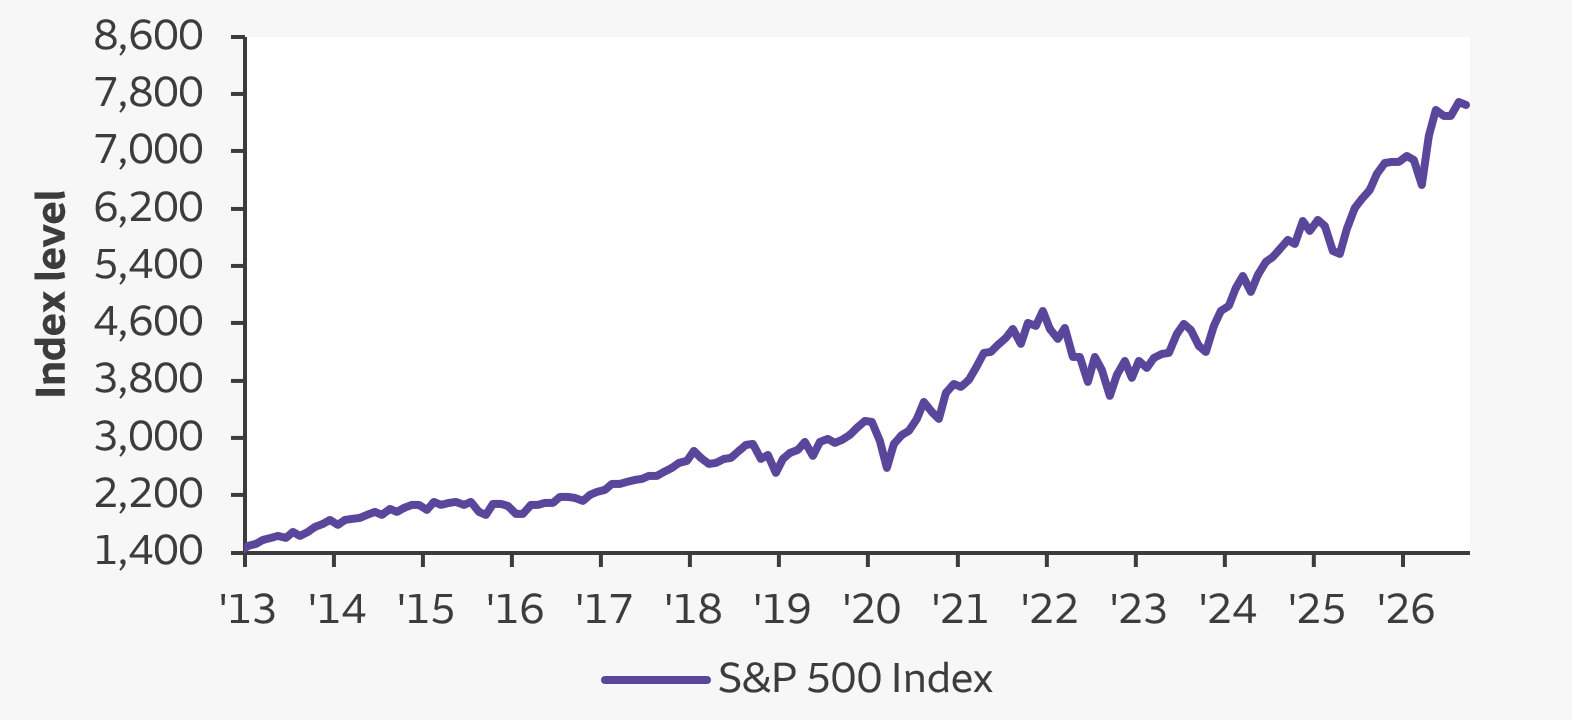
The rally has been driven by mega-cap stocks
Oil prices have risen with geopolitical turmoil
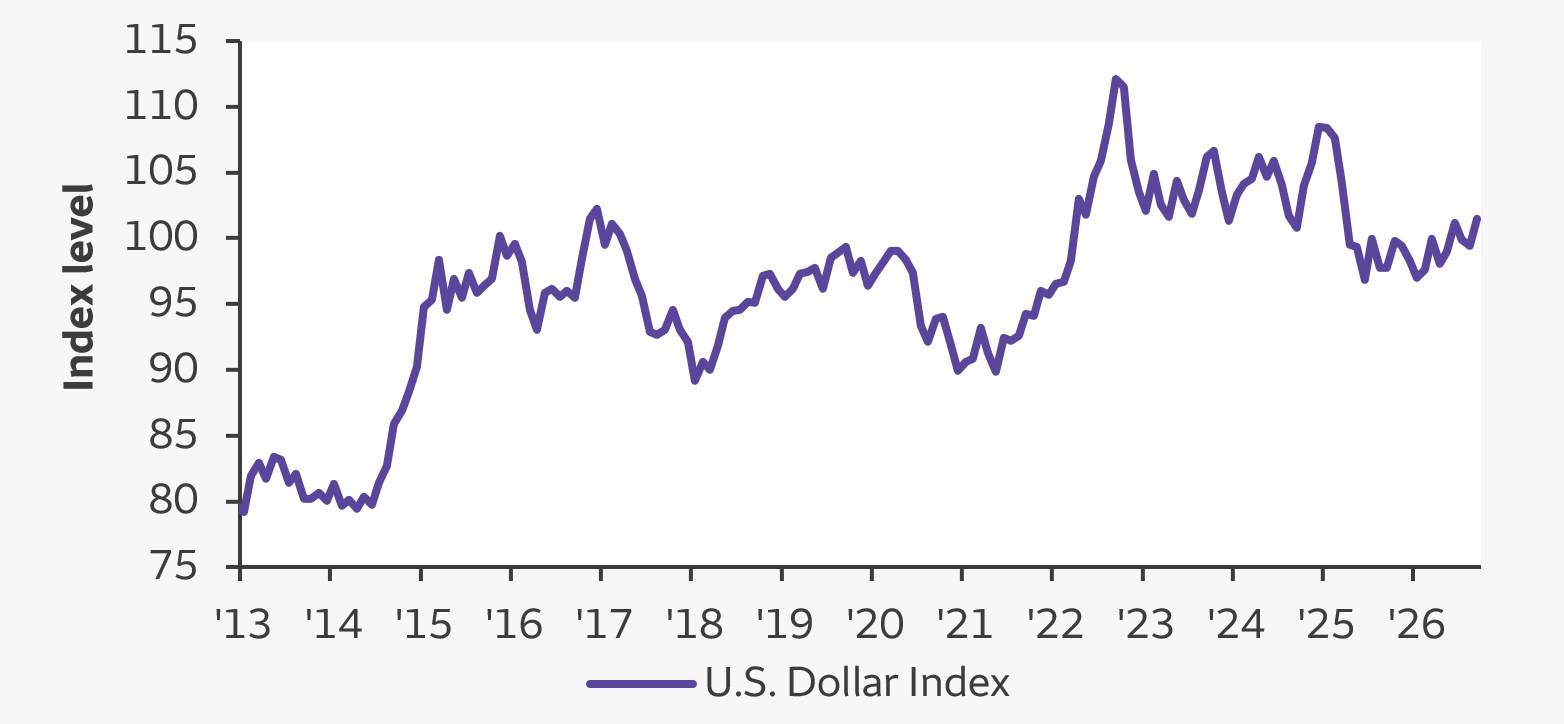
U.S. dollar has emerged as perceived safe haven asset
Inflation above Fed’s target
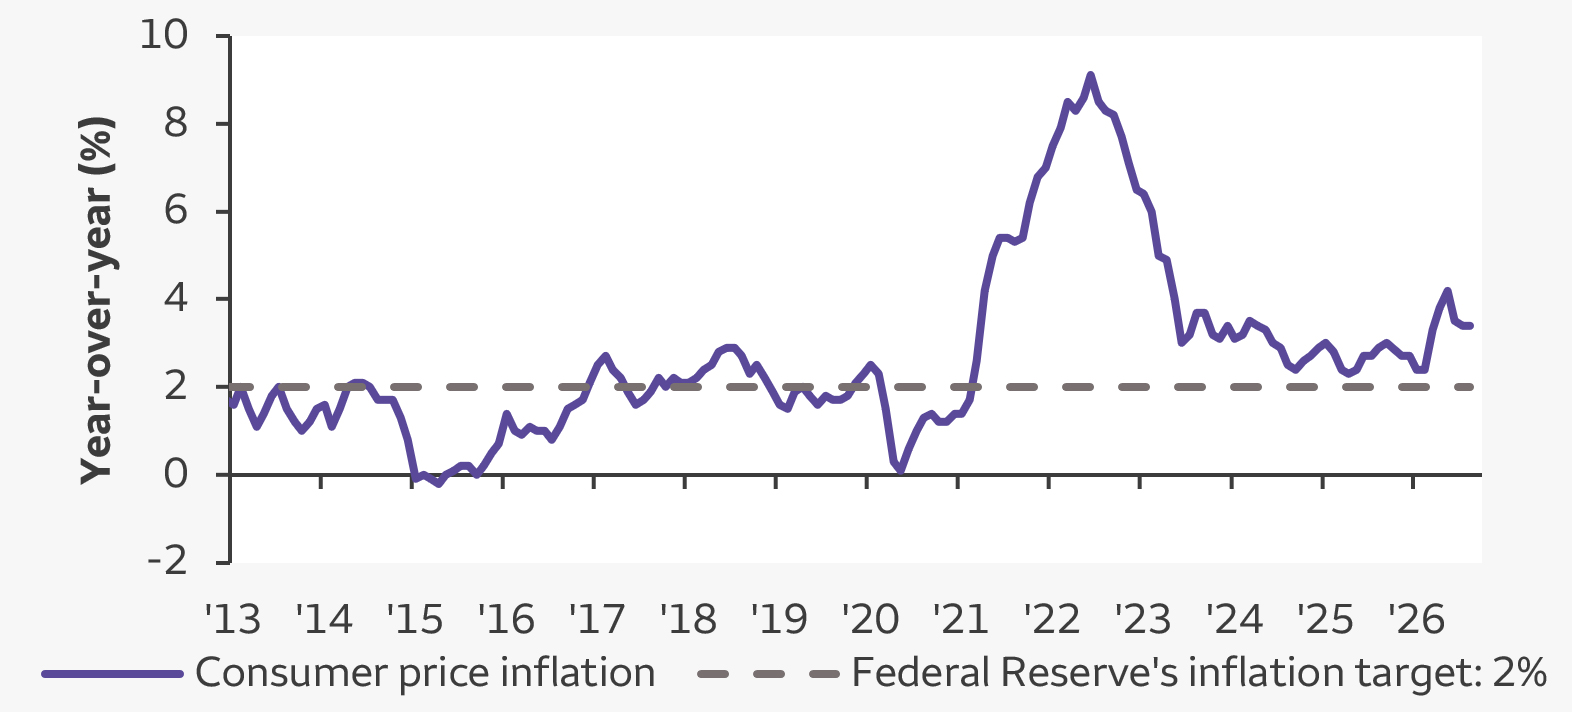 Sources: Bloomberg and Wells Fargo Investment Institute. Monthly data from January 1, 2013, to September 30, 2026. Consumer price inflation is as of August 31, 2026. Fed = Federal Reserve. The Consumer Price Index measures the average price of a basket of goods and services. The S&P 500 Index is a market capitalization-weighted index composed of 500 widely held common stocks that is generally considered representative of the U.S. stock market. West Texas Intermediate (WTI) is a grade of crude oil used as a benchmark in oil pricing. U.S. Dollar Index (USDX) measures the value of the U.S. dollar relative to the majority of its most significant trading partners. An index is unmanaged and not available for direct investment. Past performance is no guarantee of future results. Stocks may fluctuate in response to general economic and market conditions, the prospects of individual companies, and industry sectors. Currency risk is the risk that foreign currencies will decline in value relative to that of the U.S. dollar. The commodities markets are considered speculative, carry substantial risks, and have experienced periods of extreme volatility.
1 Organization of the Petroleum Exporting Countries plus allies.
Key takeaways
- We believe the U.S. economy will prove resilient through 2027, beyond a growth slowdown in late 2026 and into early 2027 tied to firmer inflation. The investment boom in artificial intelligence (AI) and related productivity gains remain key underpinnings for growth, with added support from adequate market liquidity and resilient consumer spending.
- Our outlook is becoming more sensitive to interest rates despite secular strength in AI-related investment. That could leave markets, leveraged sectors, and elevated financial assets exposed to increased volatility if liquidity conditions abruptly tighten.
Global economic forces
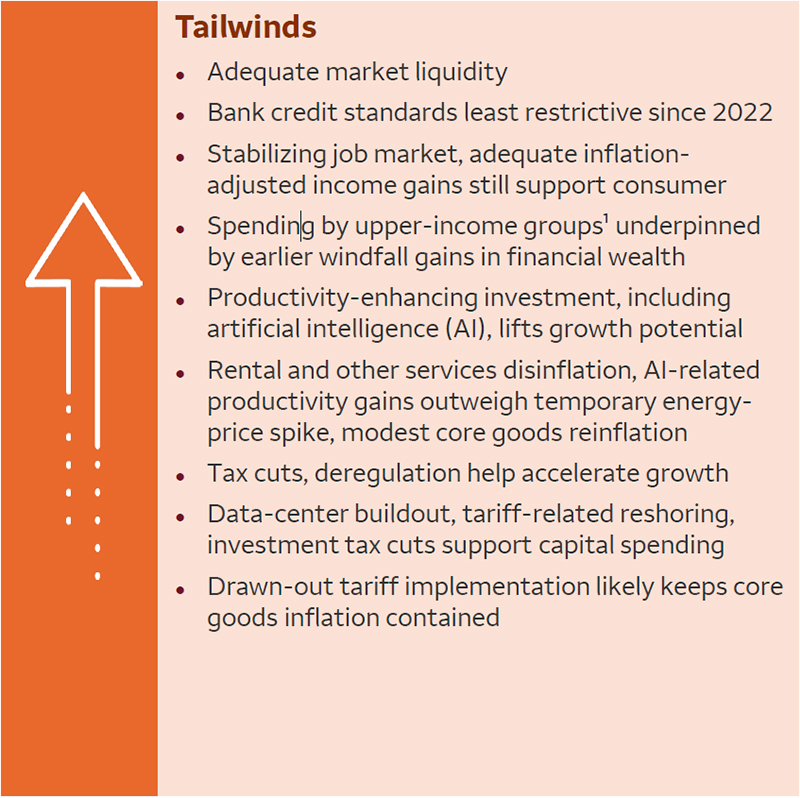
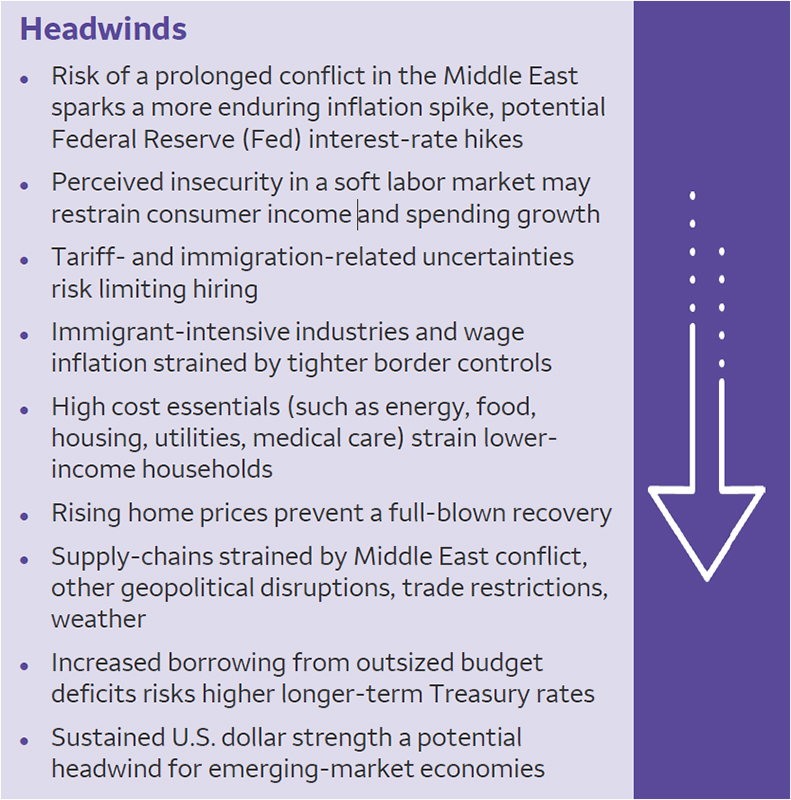 Source: Wells Fargo Investment Institute, as of September 30, 2026. Subject to change.
1 Federal Reserve Board, Financial Accounts of the U.S., as of September 11, 2026.
Key takeaways
- We believe the U.S. economy will lose momentum in late 2026 as inflation remains elevated, cushioned, however, by ongoing strength in artificial intelligence (AI)-related investment spending. Renewed disinflation during much of 2027, along with lingering policy support (centered on lower corporate taxes), should contribute to stronger growth in 2027.
- We expect the inflation spike to begin to unwind in early 2027 with price pressures in energy and other tradeable goods. In our view, energy-led disinflation in 2027 should lift consumer purchasing power and contribute to renewed growth momentum.
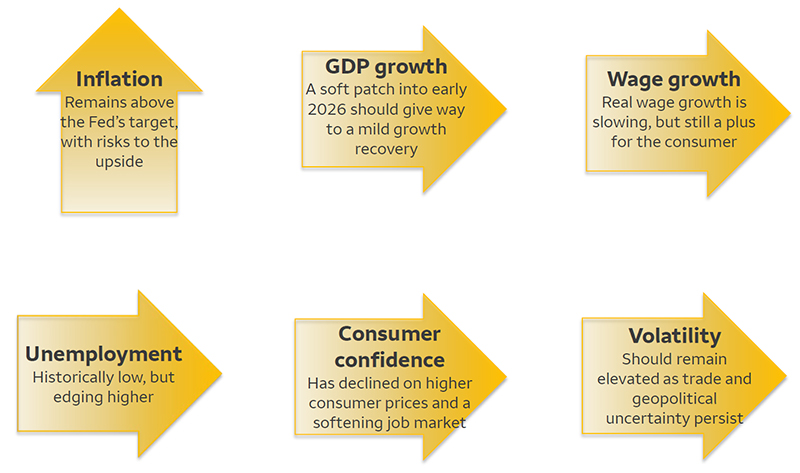 Source: Wells Fargo Investment Institute, as of September 30, 2026. Subject to change. GDP = gross domestic product. Fed = Federal Reserve.
Key takeaways
- We expect secular strength in investment spending led by artificial intelligence (AI) to cushion the U.S. economy from more than a moderate growth slowdown in late 2026. Renewed disinflation should help revive consumer-spending growth much of next year from inflation-induced pressure in late 2026-early 2027, contributing to a reacceleration of economic growth.
- We expect the U.S. stock markets to finish 2027 higher, driven primarily by earnings growth especially related to broadening investment in AI.
U.S. economic growth should recover in early 2027
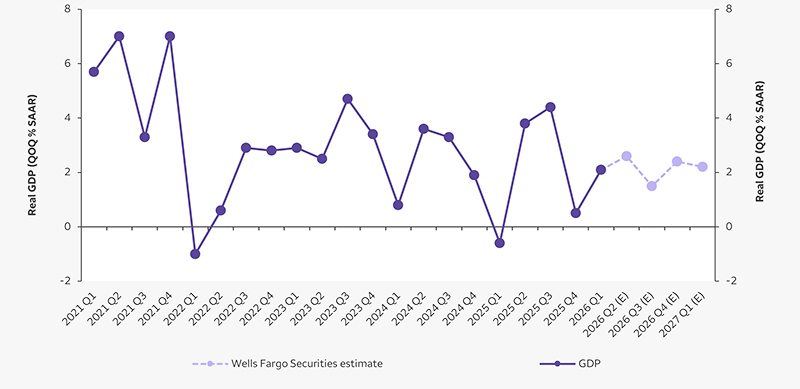 Sources: Bloomberg, Wells Fargo Securities, and Wells Fargo Investment Institute. Quarterly data from April 1, 2021, to June 30, 2026. Q3 2026 – Q4 2027 are Wells Fargo Securities forecasts, as of September 17, 2026. GDP = gross domestic product. QOQ = quarter over quarter. SAAR = seasonally adjusted annual rate. Q1 = first quarter. Q2 = second quarter. Q3 = third quarter. Q4 = fourth quarter. E = estimates. Forecasts and estimates are not guaranteed and are subject to change.
Key takeaways
- The business cycle can help investors identify where the economy may be headed and which areas of the market may be best positioned to benefit.
- Historically, leadership has shifted as growth, inflation, and interest rates evolve through each phase of the cycle. Cyclical sectors have often outperformed as growth accelerates, while defensive sectors have tended to hold up better when growth slows.
- While no cycle is identical, understanding these patterns can help investors make more informed portfolio decisions.
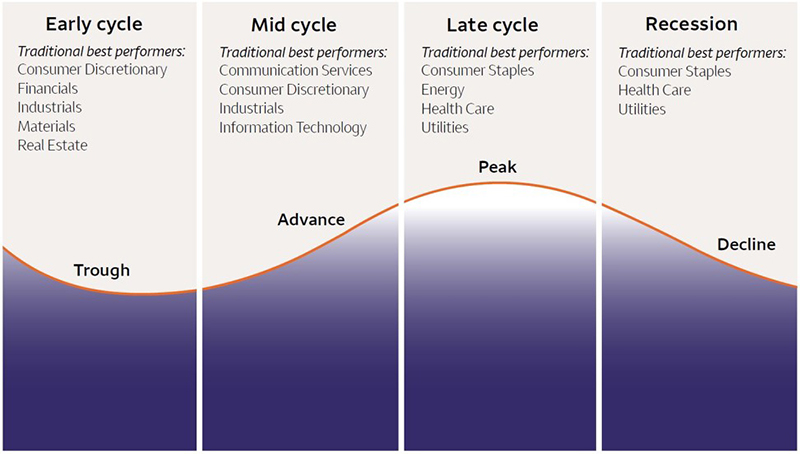 Source: Wells Fargo Investment Institute, as of September 30, 2026. Past performance is no guarantee of future results. Traditional best performers are based on the performance of S&P 500 Index sectors during a particular point in the economic cycle (early, mid, late, recession) since September 1989, the inception date for the S&P 500 sector indexes. Stocks may fluctuate in response to general economic and market conditions, the prospects of individual companies, and industry sectors. Sector investing can be more volatile than investments that are broadly diversified over numerous sectors of the economy and will increase a portfolio’s vulnerability to any single economic, political, or regulatory development affecting the sector.
Key takeaways
- Artificial intelligence (AI) and other tech investment has accounted for a disproportionate share of economic growth in recent years. By our estimate, tech investment, less than 10% of inflation-adjusted gross domestic product (GDP) in the latest four quarters, accounted for nearly 40% of GDP growth during the period, up from a 30-year norm of little more than 20%.
- Beyond investment, tech has contributed to economic growth by propelling double-digit increases in corporate profits needed to finance capital and labor expenses, and by fueling wealth-producing gains in the stock market supporting consumer spending.
AI and other tech investment are driving economic growth
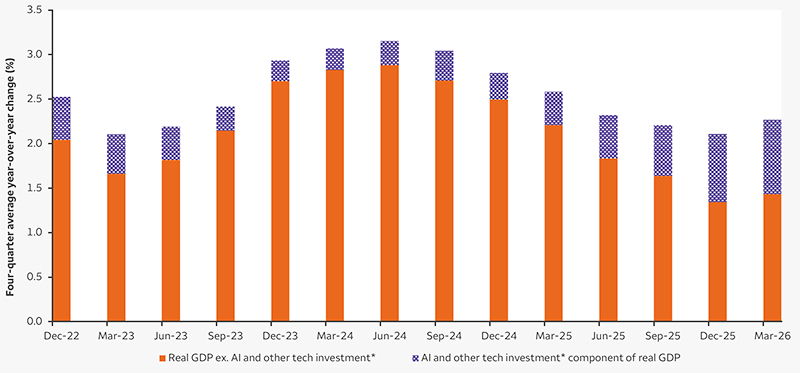 Sources: U.S. Census Bureau, U.S. Department of Commerce, and Wells Fargo Investment Institute. Quarterly data from December 31, 2022, to June 30, 2026. *Data centers, power, tech and other electronic structures, info-processing equipment & software. GDP = gross domestic product. AI = artificial intelligence.
Key takeaways
- Estimates call for the AI buildout to be more than 3% of gross domestic product (GDP) from 2025 to 2032, exceeding previous periods of large investment based on new technologies.
- Investors looking to gain exposure to the AI theme can consider U.S. Large Cap And Emerging Markets Equities, as well as the Information Technology, Communication Services, Industrials, and Utilities sectors.
Large U.S. investment periods as a percent of GDP
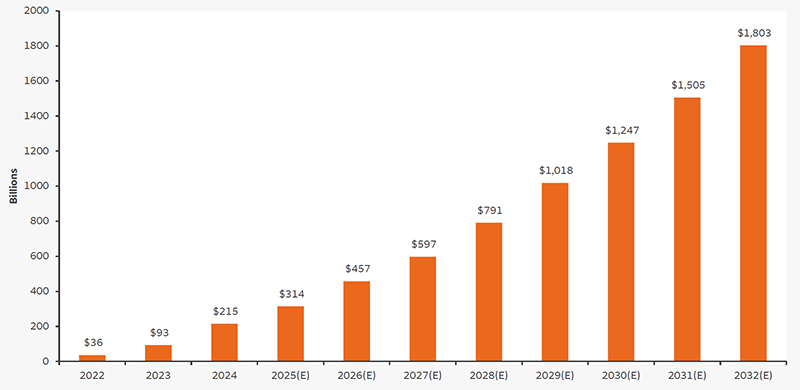 Source: Bloomberg, “AIndicators Hint at Doubts in Credit Markets”, August 10, 2026. 2025 to 2032 data are estimates. Estimates are not guaranteed and based on certain assumptions and on views of market and economic conditions which are subject to change.
Key takeaways
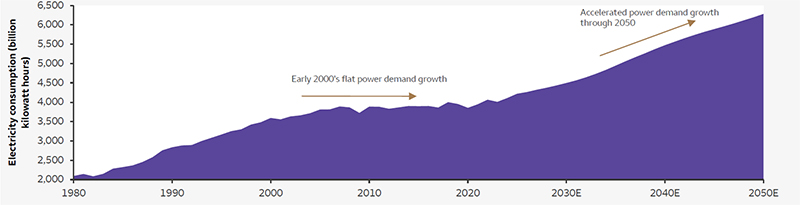
- The adoption of emerging technologies such as artificial intelligence (AI), and the required data centers and electrification for them, are driving higher demand for power generation.
- Following over a decade of minimal power demand growth, we believe demand for power generation will be a strong tailwind for Energy sector performance as the buildout of these energy-intensive technologies continues to grow.
Power demand inflecting higher
Artificial-intelligence (AI) data centers require massive amounts of power
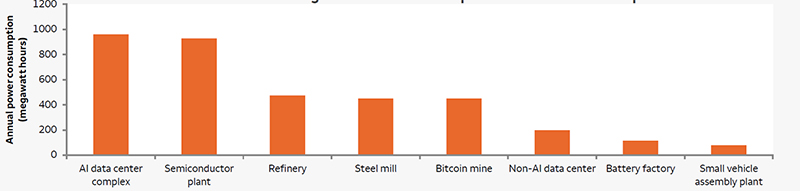 Sources: Top chart: U.S. Energy Information Administration (EIA) and Wells Fargo Investment Institute. Annual data from January 1, 1980, to December 31, 2024. EIA forecast data from 2025 – 2050 as of September 30, 2026. Total renewables includes hydro, geothermal, wind, solar, and biomass primary energy consumption. E = estimate. Estimates are not guaranteed and based on certain assumptions and on views of market and economic conditions which are subject to change. Bottom chart: Company reports, Syracuse website, wvmetronews website, KERANews, AFL Hyperscale, Assembly Magazine, Energy Star, and Wells Fargo Investment Institute. Data as of June 30, 2026.
Key takeaways
- While market sentiment has stretched tech valuations, they are nowhere near the levels reached in 2000, at the height of the tech bubble.
S&P 500 Index P/Es now versus during the tech bubble
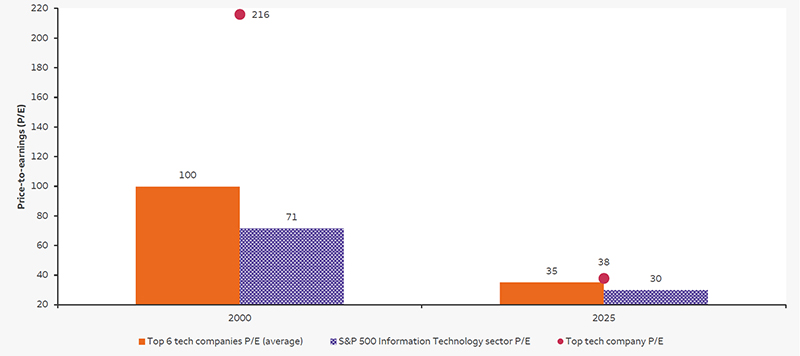 Sources: Bloomberg and Wells Fargo Investment Institute. Monthly data from March 27,2000, to September 30, 2026. P/E = price to earnings. Trailing 12-month P/E ratio is displayed. Top 6 measured as the top six tech companies by market cap as of March 27, 2000, to March 31, 2026. The S&P 500 Index is a market-capitalization-weighted index considered representative of the U.S. stock market. An index is unmanaged and not available for direct investment. Past performance is no guarantee of future results. Stocks may fluctuate in response to general economic and market conditions, the prospects of individual companies, and industry sectors. Technology and Internet-related stocks, especially smaller, less-seasoned companies, tend to be more volatile than the overall market.
Key takeaways
- The yield curve has been largely influenced by current fiscal and monetary policy, but this year, it also experienced downward and upward shifts due to geopolitical and war concerns.
- We expect any increases in short-maturity bond yields to be outweighed by rising long-maturity yields, driven by strong U.S. economic growth, sticky inflation, and rising term premiums.
Yield curve steepness: Difference between 30-year and 2-year U.S. Treasury yields
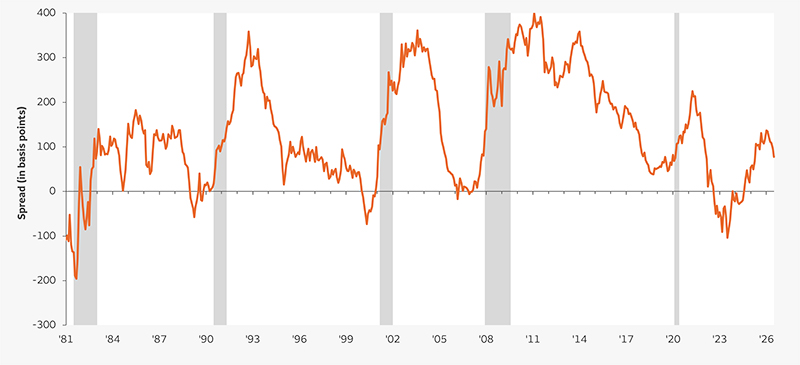 Sources: Bloomberg, and Wells Fargo Investment Institute. Monthly data from January 1, 1981, to September 30, 2026. Thirty-Year Treasury Constant Maturity and the Two-Year Constant Maturity Indexes are published by the Federal Reserve Board and are based on the average yield of a range of Treasury securities, all adjusted to the equivalent of a 30-year maturity and the equivalent of a two-year maturity. Shaded area represents time frame of a U.S. economic recession. Yields represent past performance and fluctuate with market conditions. Current yields may be higher or lower than those quoted above. Past performance is no guarantee of future results. 100 basis points equal 1%. Although Treasuries are considered free from credit risk, they are subject to other types of risks. These risks include interest rate risk, which may cause the underlying value of the bond to fluctuate.
Key takeaways
- Real rates on the 10-year U.S. Treasury have been in positive territory since May 2022 as 10-year breakeven inflation rate readings fell below nominal rates. We expect real rates to remain positive, especially if nominal rates remain elevated.
- Rising yields may provide opportunity to gain higher income from shorter term bonds (one- to three-year maturities) while limiting exposure to continued volatility we see in longer-term maturities.
Deconstructing the 10-year nominal U.S. Treasury note
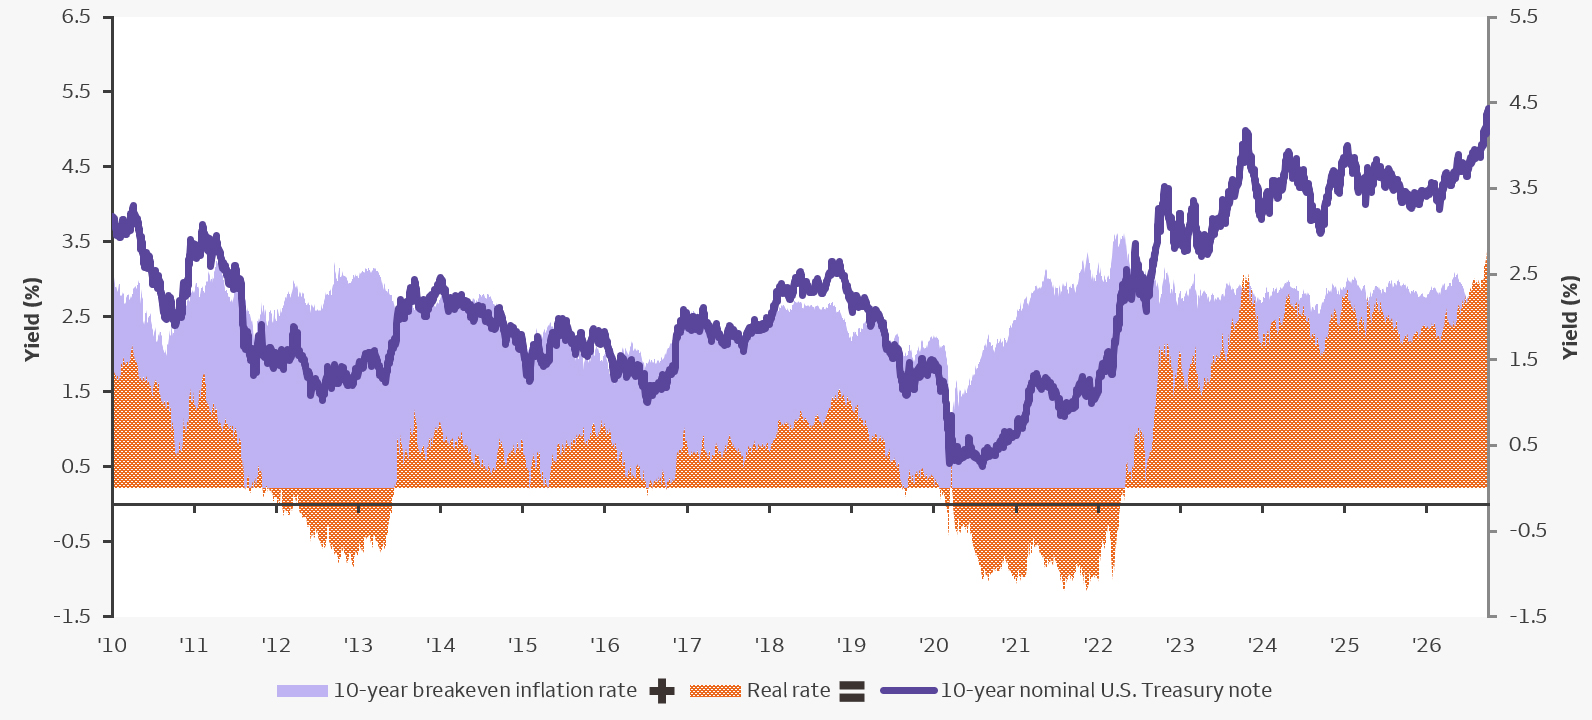 Sources: Bloomberg and Wells Fargo Investment Institute. Daily data from January 1, 2010, to September 30, 2026. Yields represent past performance and fluctuate with market conditions. Current yields may be higher or lower than those quoted above. Past performance is no guarantee of future results. Although Treasuries are considered free from credit risk, they are subject to other types of risks. These risks include interest rate risk, which may cause the underlying value of the bond to fluctuate.
Key takeaways
- The equity risk premium is the additional return investors expect to earn from stocks over a risk-free investment as compensation for taking on the greater risk of owning equities.
- A lower equity risk premium does not automatically signal trouble for stocks. Valuations are notoriously poor timing tools, and with the equity risk premium near its long-term average, we believe continued earnings growth can support further gains even if valuation expansion moderates.
S&P 500 Index equity risk premium
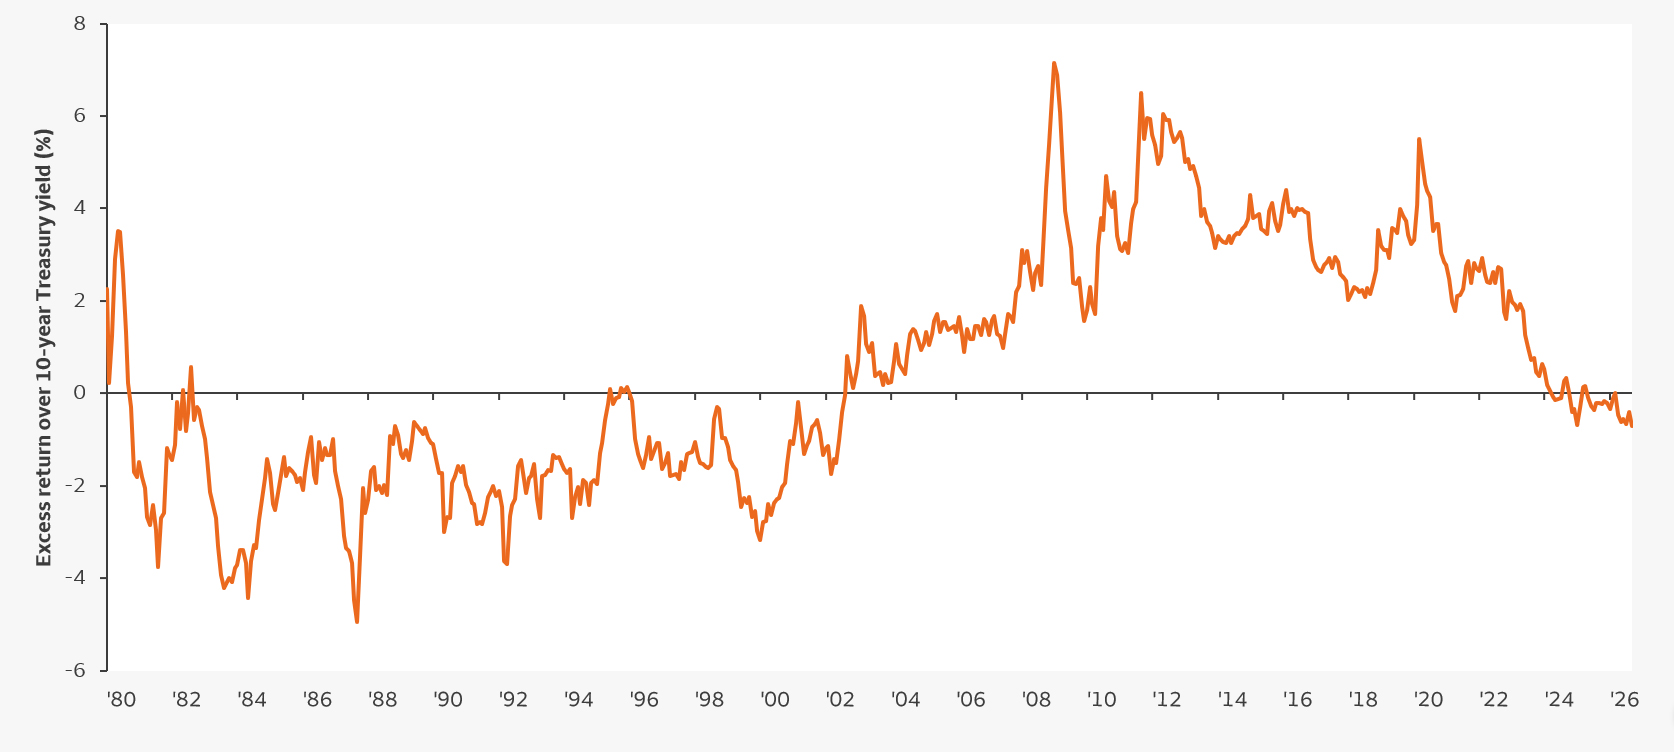 Sources: Bloomberg and Wells Fargo Investment Institute. Monthly data from January 1, 1980, to September 30, 2026. The S&P 500 Index is a market-capitalization-weighted index considered representative of the U.S. stock market. An index is unmanaged and not available for direct investment. Past performance is no guarantee of future results. Stocks may fluctuate in response to general economic and market conditions, the prospects of individual companies, and industry sectors.
Asset allocation cannot eliminate the risk of fluctuating prices and uncertain returns. Diversification cannot eliminate the risk of fluctuating prices and uncertain returns.
Equity investments: Stocks offer long-term growth potential but may fluctuate more and provide less current income than other investments. An investment in the stock market should be made with an understanding of the risks associated with common stocks, including market fluctuations.
Fixed income: Investments in fixed-income securities are subject to interest rate, credit/default, liquidity, inflation, prepayment, extension, and other risks. Bond prices fluctuate inversely to changes in interest rates. Therefore, a general rise in interest rates can result in a decline in the bond’s price. Credit risk is the risk that an issuer will default on payments of interest and/or principal. High-yield fixed-income securities (junk bonds) are considered speculative, involve greater risk of default, and tend to be more volatile than investment-grade fixed-income securities. If sold prior to maturity, fixed-income securities are subject to market risk. All fixed-income investments may be worth less than their original cost upon redemption or maturity.
Foreign investments: Investing in foreign securities presents certain risks not associated with domestic investments, such as currency fluctuation, political and economic instability, and different accounting standards. This may result in greater share price volatility. These risks are heightened in emerging markets.
Sector investing can be more volatile than investments that are broadly diversified over numerous sectors of the economy and will increase a portfolio’s vulnerability to any single economic, political, or regulatory development affecting the sector. This can result in greater price volatility. Communication services companies are vulnerable to their products and services becoming outdated because of technological advancement and the innovation of competitors. Companies in the communication services sector may also be affected by rapid technology changes; pricing competition, large equipment upgrades, substantial capital requirements and government regulation and approval of products and services. In addition, companies within the industry may invest heavily in research and development which is not guaranteed to lead to successful implementation of the proposed product. The Energy sector may be adversely affected by changes in worldwide energy prices, exploration, production spending, government regulation, and changes in exchange rates, depletion of natural resources, and risks that arise from extreme weather conditions. There is increased risk investing in the Industrials sector. The industries within the sector can be significantly affected by general market and economic conditions, competition, technological innovation, legislation and government regulations, among other things, all of which can significantly affect a portfolio’s performance. Risks associated with the Technology sector include increased competition from domestic and international companies, unexpected changes in demand, regulatory actions, technical problems with key products, and the departure of key members of management. Technology and Internet-related stocks, especially smaller, less-seasoned companies, tend to be more volatile than the overall market. Utilities are sensitive to changes in interest rates, and the securities within the sector can be volatile and may underperform in a slow economy.
Global Investment Strategy (GIS) is a division of Wells Fargo Investment Institute, Inc. (WFII). WFII is a registered investment adviser and wholly owned subsidiary of Wells Fargo Bank, N.A., a bank affiliate of Wells Fargo & Company.
The information in this report was prepared by GIS. Opinions represent GIS’ opinion as of the date of this report; are for general information purposes only; and are not intended to predict or guarantee the future performance of any individual security, market sector, or the markets generally. GIS does not undertake to advise you of any change in its opinions or the information contained in this report. Wells Fargo & Company affiliates may issue reports or have opinions that are inconsistent with, and reach different conclusions from, this report.
The information contained herein constitutes general information and is not directed to, designed for, or individually tailored to any particular investor or potential investor. This material is not intended to be a client-specific suitability or best interest analysis or recommendation; an offer to participate in any investment; or a recommendation to buy, hold, or sell securities. Do not use this information as the sole basis for investment decisions. Do not select an asset class or investment product based on performance alone. Consider all relevant information, including your existing portfolio, investment objectives, risk tolerance, liquidity needs, and investment time horizon.
Wells Fargo Securities is the trade name for the capital markets and investment banking services of Wells Fargo & Company and its subsidiaries, including Wells Fargo Securities, LLC, member NYSE, FINRA and SIPC and Wells Fargo Bank, National Association.
Wells Fargo Advisors is registered with the U.S. Securities and Exchange Commission and the Financial Industry Regulatory Authority but is not licensed or registered with any financial services regulatory authority outside of the U.S. Non-U.S. residents who maintain U.S.-based financial services accounts with Wells Fargo Advisors may not be afforded certain protections conferred by legislation and regulations in their country of residence in respect of any investments, investment transactions, or communications made with Wells Fargo Advisors.
Wells Fargo Advisors is a trade name used by Wells Fargo Clearing Services, LLC, and Wells Fargo Advisors Financial Network, LLC, Members SIPC, separate registered broker/dealers and nonbank affiliates of Wells Fargo & Company.
© 2026 Wells Fargo Investment Institute. All rights reserved.